Home is not a guaranteed hedge
Home is not a guaranteed hedge
Why global diversification may be Europe’s next pension defense strategy
This op-ed originally appeared in Investment & Pensions Europe.
Having spent more than two decades in asset management and private wealth, I have watched investors become more nuanced in the way they think about risk. What once appeared prudent can start to look less safe when the world changes around it. Today, that is increasingly true of portfolios that remain concentrated close to home.
For many European pension savers, emerging markets still carry the label of risk. The instinctive response can be to favor domestic or regional assets, especially in uncertain times. Yet concentration is also a risk. When portfolios are heavily exposed to the same geographies, currencies, fiscal cycles and demographic pressures as the liabilities they are meant to fund, they can become more vulnerable, not less.
This is why the diversification debate feels particularly timely. Europe is navigating a more fragmented global economy, renewed inflation concerns, higher defense and security spending, and a demographic profile that will place growing pressure on pension systems over time. EU defense spending reached €418 billion in 2025, up 20% from the previous year, and is projected to rise to €454 billion in 2026, equivalent to 2.4% of GDP. In such an environment, investing abroad should not be seen as a departure from prudence. It can be part of how long-term investors protect purchasing power, manage concentration risk and access growth drivers that are not available in the same form at home.
The starting point is home bias. Pension allocations often reflect familiarity, regulation, governance comfort and legacy market structures. None of these are irrational. But familiarity can create blind spots and lead to a deceptive sense of security. A portfolio that appears conservative because it is invested in familiar markets may in fact be highly exposed to the same macroeconomic shocks: slower regional growth, fiscal strain, political uncertainty, energy costs or rising public debt.
For pension investors, this matters because the objective is not simply to avoid volatility in the next quarter. It is to meet obligations across decades. That requires portfolios that are resilient to different economic scenarios. Demographics alone make this challenge more complex. OECD analysis shows that across member countries there were 33 people aged 65 and older for every 100 people aged 20 to 64 in 2025, a figure expected to rise to 52 by 2050. In the EU, more than one-fifth of the population was already aged 65 or above in 2025, in stark contrast to the demographic profile and outlook of many emerging markets. A smaller working-age population, higher age-related spending and slower trend growth all make the search for diversified sources of return more important.
At the same time, Europe’s security environment is changing the fiscal backdrop. Higher defense and infrastructure spending may be necessary, but it also changes the investment landscape. More public borrowing, competing budget priorities, and a potentially more inflation-prone environment can affect domestic bond markets, growth expectations, and the balance between public and private capital. For pension funds, that makes geographic diversification less of an optional enhancement and more of a portfolio discipline.
This does not mean replacing one concentration with another. Nor does it mean treating emerging markets as a single risk trade. The more useful lens is diversification across different growth trajectories, sector exposures, demographic profiles, and financial systems. The IMF expects advanced economies to grow by around 1.5% in 2026, compared with just above 4% for emerging markets and developing economies. Some emerging markets are being shaped by young populations and expanding consumer bases. Others are central to food security, renewable energy, digital infrastructure, supply-chain realignment, or climate adaptation. These are not identical stories, but parts of the mosaic, and that is precisely the point.
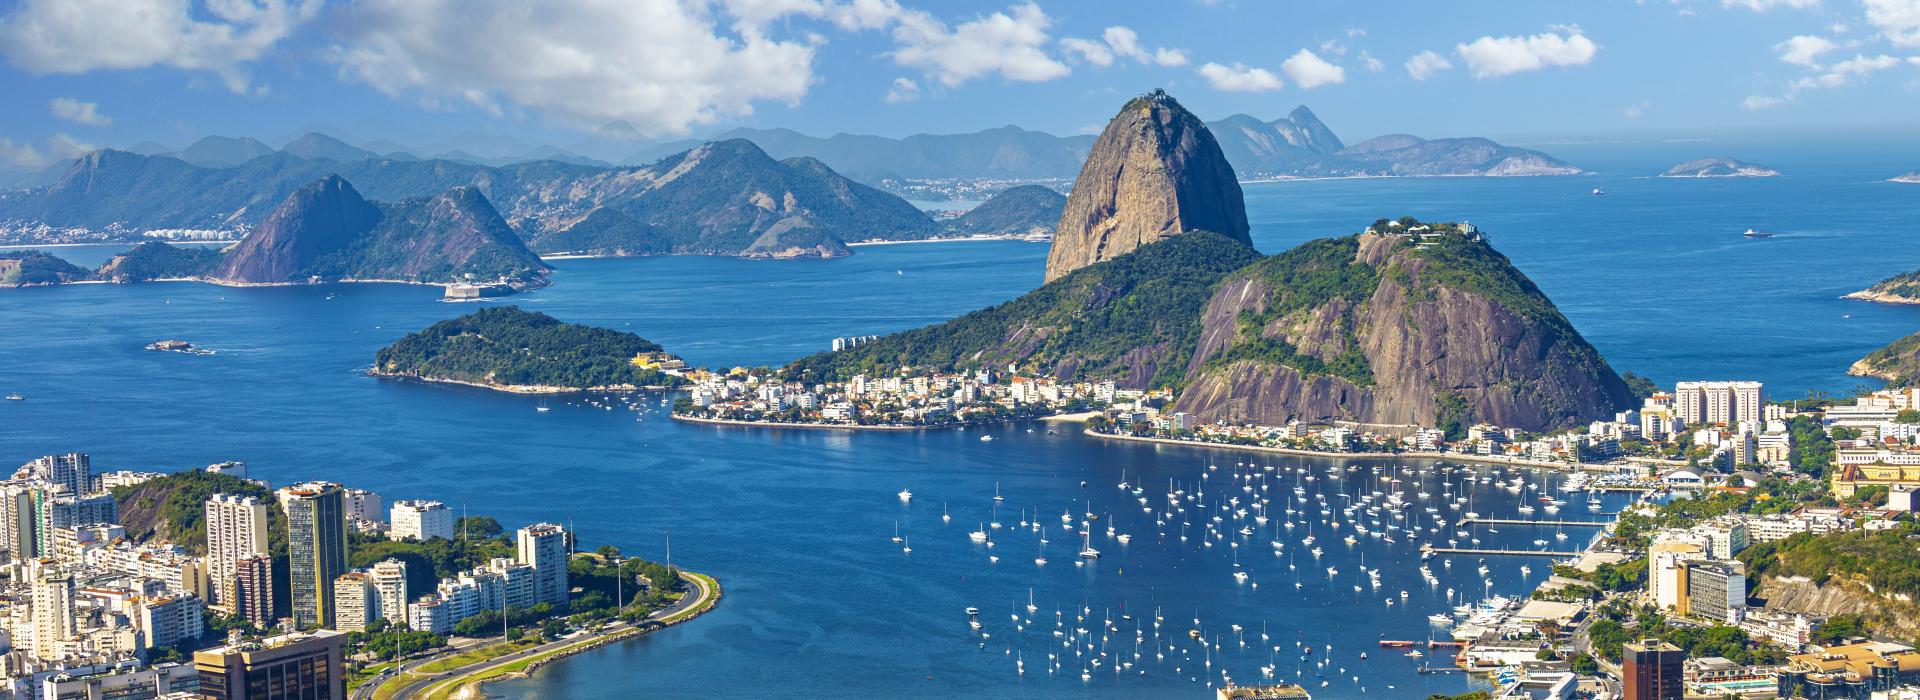
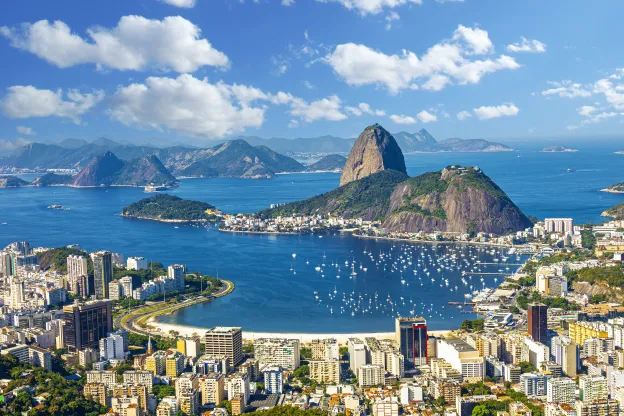
Brazil is a useful example of what this can look like in practice. It is not compelling because it is free of risk; no major market is. It is compelling because its investment case is built on different foundations from those of Europe. Brazil combines Latin America’s largest economy with a deep domestic market, a globally relevant agricultural sector and one of the cleanest power systems among major economies. In 2025, around 89% of Brazil’s electricity came from low-carbon sources, with wind and solar together accounting for more than a quarter of generation. Agribusiness exports reached a record of US$169.2 billion in 2025, underscoring the country’s role in global food supply chains. For investors seeking resilience, these characteristics matter because they link returns to structural themes—food security, renewable power, resource efficiency and domestic demand—that are not simply mirrors of Europe’s economic cycle.
Brazil also shows why the emerging-market discussion needs nuance. Fiscal constraints, interest-rate cycles, and political uncertainty still require careful underwriting. But for long-term pension investors, the point is not to ignore those risks. It is to ask whether they are being compensated for exposures that behave differently from domestic European assets and that may broaden the portfolio’s sources of return. In that sense, Brazil is less an exception than an illustration of the broader argument: diversification works best when it gives investors access to fundamentally different economic engines.
The strongest argument for emerging market exposure is therefore not that these markets are immune to volatility. They are not. It is that they can offer exposure to different economic engines than those driving European assets. In a world where developed markets can be highly correlated during periods of stress, the ability to access distinct sources of return becomes valuable. Diversification is not about avoiding risk altogether; it is about avoiding the wrong kind of risk: the risk that too much of a portfolio depends on the same assumptions being right.
For European pension savers, this distinction is critical. Their retirement outcomes are already tied to domestic wages, employment, tax policy, public finances, and inflation. If their pension assets are also overwhelmingly exposed to the same region, the protection that long-term investing is meant to provide can be weakened. Global allocation can create a second line of defense by linking future retirement income to a broader set of economies and sectors.
Of course, diversification only works when it is done with discipline. Investing abroad requires local knowledge, thoughtful structuring, currency awareness, governance standards, and experienced partners who understand both the opportunities and the practical realities on the ground. The objective is not simply to add countries to a map. It is to build portfolios that can withstand scrutiny from investment committees and contribute to long-term outcomes for savers.
This is where emerging-market private credit, real-economy financing, and sustainable investment strategies can play a constructive role. They can channel capital into areas where financing needs are significant and where growth is linked to structural themes rather than short-term market cycles. For institutional investors, the attraction lies not in a simple yield story, but in the combination of diversification, risk-adjusted return potential and exposure to sectors that are underrepresented in traditional European portfolios.
The shift in language matters. Emerging markets should not be framed as the adventurous corner of a portfolio, or as a risk allocation that sits apart from the core objective. For long-term investors, they can be part of the resilience toolkit. They offer access to different productivity cycles, domestic demand patterns, resource endowments, and transition needs. Used carefully, they can help reduce dependence on any single region’s fiscal and demographic outlook.
That is why I think the question for pension investors is changing. It is not whether investing abroad introduces risk. Every allocation does. The more relevant question is whether staying too close to home leaves portfolios insufficiently prepared for the world their savers will retire into. In an era of fragmentation, fiscal pressure, ageing populations and uneven growth, resilience may depend on looking beyond familiar markets and resisting the siren's song of normalcy bias.
After more than two decades in this industry, I have learned that prudence is not static. It changes as risks change. For European pension investors, diversification is increasingly more than a portfolio principle. It is a defense strategy: a way to protect savers at home by ensuring their futures are not tied too narrowly to the fortunes of home alone.
About the author:
Melanie Aimer is the Chief Commercial Officer at Finance in Motion and has over 20 years of experience leading global teams across Corporate & Investment Banking, Asset Management, Private Banking and Wealth Management.